
Business Loan Application Singapore: How SMEs Should Prepare
Overview
- A business loan application Singapore lenders accept starts with a clear financial story, not just a stack of papers. Lenders look at revenue trends, profitability, cash flow, existing debt, credit history, operating history and how you plan to use the money.
- Gather the core SME loan documents Singapore lenders usually ask for: ACRA business profile, latest financial statements, recent bank statements, management accounts, existing loan details, directors’ IDs and Notices of Assessment, ageing reports and papers that explain the funding purpose.
- Review your books before you apply. Up to date records and matching figures across every document cut down on follow up questions.
- Estimate the amount you need, then test whether your cash flow can carry the monthly repayments with some room to spare.
- Match the product to the purpose. A working capital loan suits daily cash flow, a term loan suits planned investment and trade financing suits eligible trade deals. Compare total cost, not only the advertised interest rate.
- Requirements differ between lenders and loan products, and no one can promise approval. Use the checklist at the end of this guide to check your readiness.
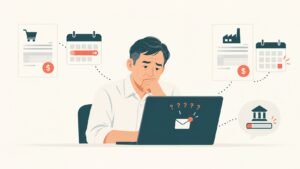
Picture Mr Tan, who runs a small trading company in Singapore. His customers pay in 60 days, but his suppliers want payment in 14. Sales look healthy, yet his bank balance keeps dipping. He decides to apply for a loan, fills in the form in one afternoon, and then waits. A week later, the lender emails him with five questions about his bank statements and one unexplained gap in his accounts.
Sound familiar? Many owners treat business loan preparation Singapore as a paperwork exercise. In reality, lenders try to answer one simple question: can this business repay the loan comfortably? Your job is to make that answer easy to see. This guide walks you through each step in plain language, so you can approach SME financing Singapore with confidence and fewer surprises.
Step 1: Understand What Lenders Assess
Lenders assess whether your business can repay the loan on time, and they judge this from your financial track record, your current obligations and your plans. Each lender weighs these factors differently, but most look at the following.
- Revenue trends: Are sales growing, steady or falling over the last two to three years? A dip is not a deal breaker, but you should be ready to explain it.
- Profitability: Does the business earn a profit after paying its costs? Lenders compare your profit margins with typical results in your industry.
- Cash flow: This is the real money moving in and out of your bank account. Profit on paper does not help if customers pay late. Cash flow often matters most when a lender thinks about repayment.
- Existing debt commitments: Lenders add up your current loans, hire purchase, credit lines and credit card balances to see how much room you have for a new instalment.
- Credit history: Lenders may check the company’s payment record and the directors’ personal credit reports through the Credit Bureau Singapore. Paying bills on time builds trust.
- Business stability: How long have you operated? Do you depend on one or two big customers? Is your management team steady? A longer, steadier history usually helps.
- Intended use of funds: A clear purpose, such as buying stock for confirmed orders, gives lenders more confidence than a general request for cash.
Please remember that business loan requirements Singapore lenders set will vary. A bank, a non-bank lender and a government-supported scheme each use different rules for minimum operating history, turnover, ownership and security. For example, the Enterprise Financing Scheme for SME working capital from Enterprise Singapore requires the business to be registered and operating in Singapore and to meet a local equity requirement, and each participating financial institution makes its own credit decision. Always check the latest terms on the official page before you apply, because schemes change from time to time.
In short, business loan eligibility Singapore is never one fixed checklist. It depends on the lender, the loan type and your financial profile.
Step 2: Prepare the Essential Documents
The core documents for most applications are your ACRA profile, financial statements, bank statements, loan details, director identification and papers that explain why you need the funds. The table below shows what each one does and why lenders care. Lenders may ask for more or fewer items, so treat this as a strong starting list.
| Document | What it shows | Why it matters |
| ACRA business profile and company information | Company name, UEN, incorporation date, directors, shareholders and paid up capital | Confirms who owns and runs the business, and that the company is legally registered |
| Latest financial statements (profit and loss, balance sheet) | Revenue, expenses, profit, assets, liabilities and equity | Gives lenders the main picture of performance and financial strength |
| Recent company bank statements | Actual money in and out, usually for the last 6 to 12 months | Proves your cash flow in real life and shows your repayment habits |
| Management accounts and updated records | Your figures for the months since your last year end | Shows the business today, not only last year’s results |
| Existing loan and repayment details | Lender, balance, instalment, interest and end date for each facility | Helps lenders work out how much more debt the business can carry |
| Directors’ or guarantors’ ID and personal Notice of Assessment | Identity and the personal income declared to IRAS | Used where the lender needs a personal guarantee or checks directors’ finances |
| Debtors and creditors ageing reports | Who owes you, who you owe, and how overdue each amount is | Shows how fast customers pay and how well you manage supplier bills |
| Business plan, quotations, purchase orders or contracts | The reason for the loan and the expected result | Backs up your funding purpose with evidence |
How to get your ACRA business profile (step by step)
Many owners find this part confusing, so here is a simple walk through. You can do it on a computer or a phone.
- Open your web browser and type gov.sg in the address bar. You can also visit the ACRA guide to buying a Business Profile for pictures of each screen.
- Use the search box to type your company name or your UEN (the Unique Entity Number printed on your registration documents).
- Click the result that matches your company, then click “Add to cart” for the Business Profile.
- Pay by credit card, debit card or online banking. ACRA lists the fee at S$5.50 at the time of writing, but please check the current price on the page.
- Check your email. ACRA usually sends a download link within about 15 minutes. Click the link and save the PDF in a folder you can find again.
How to download a director’s Notice of Assessment from myTax Portal
- Go to iras.gov.sg on your computer. The IRAS myTax Portal is the official site, so please check the address carefully before you key in any details.
- Choose the personal tax login and sign in with Singpass. Use the Singpass app on your phone to scan the QR code, or key in your Singpass ID and password and then complete the two step verification.
- Look for the Notices menu, choose Individual, then click View Individual Tax Notices.
- Pick the latest Year of Assessment and click on the Notice of Assessment. Download it and save it as a PDF. Menu names can change slightly over time, and IRAS publishes step by step user guides on its website if your screen looks different.
Tips for the other documents
- Bank statements: Log in to your company’s internet banking, look for “Statements” or “e-Statements”, and download one PDF for each month. Ask your lender how many months they want.
- Ageing reports: Most accounting software, such as Xero or QuickBooks, can print an “Aged Receivables” and an “Aged Payables” report in a few clicks. If you use Excel, your accountant can prepare these for you.
- Audited or unaudited accounts: Many small companies qualify for audit exemption, so lenders may accept unaudited financial statements together with management accounts. Policies vary, so confirm this early.
Step 3: Review Your Financial Position Before Applying
Check your records yourself before a lender does. A quick review often finds small problems that are easy to fix today but hard to explain later. Work through these four checks.
1. Are your financial statements up to date?
Look at the date on your latest financial statements. If they are more than a year old, lenders will probably ask for management accounts for the months since. Ask your accountant to prepare them before you apply, so you do not lose time later.
2. Are your bank transactions properly recorded?
Compare your bookkeeping with your bank statements for the last six months. Every deposit and payment should match an invoice, a bill or a clear note. Unrecorded transactions, personal spending paid from the company account and large cash withdrawals with no explanation all raise questions.
3. Do you monitor your outstanding receivables?
Print your aged receivables report and see which customers owe you money and for how long. Invoices overdue by more than 90 days may worry a lender. Follow up with those customers now, and note any good reason for a delay, such as a dispute that you have since settled.
4. Do the figures match across all documents?
Revenue in your financial statements, your management accounts, your GST returns and your bank deposits should tell the same story. They will not match to the dollar, because of timing and GST, but you should be able to explain every major difference. Write a short note that lists the reasons.
Incomplete bookkeeping or unexplained gaps usually lead to extra questions, longer processing time and, in some cases, a weaker application. Clean records show that you manage the business with care, and that gives a lender more comfort.
Step 4: Calculate Your Funding Needs and Repayment Capacity
Borrow the amount your business actually needs, and borrow only what your cash flow can repay. Too little funding leaves you short again within months. Too much funding adds interest and pressure that you do not need. Follow these four steps.
- Write down the purpose in one sentence. For example: “Buy S$50,000 of stock for the year end peak season.”
- Work out the amount. Add the cost of the item or project, plus related costs such as delivery and insurance. Then subtract the cash you can use from your own funds and keep a small buffer.
- Set the timeline. Ask when the money will come back to the business. Stock bought today may turn into cash in three months, while new equipment may pay off over three years. The repayment period should fit this timeline.
- Test your repayment capacity. Take your average monthly cash available for repayment, which is the cash your business generates after paying operating costs, tax and existing instalments. Divide it by the new monthly instalment. Many lenders like to see a comfortable cushion, and some use a rule of thumb of at least 1.25 times, but each lender sets its own standard.
Practical example: a working capital loan to buy inventory
Let us say Lim’s Kitchenware Pte Ltd sells to retailers. The company wants to stock up before the year end sales season, and its customers owe it S$85,000 on invoices that will only be paid in about 60 days. Meanwhile, suppliers want payment for new stock now. The numbers look like this.
| Item | Amount (illustrative) |
| Stock purchase needed now | S$50,000 |
| Customer invoices outstanding, due in about 60 days | S$85,000 |
| Average monthly cash from operations, before the new loan | S$12,000 |
| Existing loan instalments each month | S$2,000 |
| Cash available for new repayments each month | S$10,000 |
| Proposed loan: S$50,000 over 12 months at an assumed 8% a year | About S$4,350 a month |
| Total repayment for the loan (illustrative) | About S$52,200 |
| Cash available divided by new instalment | About 2.3 times |
Here the company can show three things clearly: why it needs the money (stock for confirmed demand), where the repayment comes from (monthly cash flow plus the S$85,000 of invoices it expects to collect), and that its cash flow covers the new instalment more than twice. These figures are examples only, and actual interest rates, fees and terms depend on the lender and the company’s profile. The company can also repay early if the invoices come in sooner, subject to the lender’s terms, so it should ask about early repayment fees.
If your own numbers look tight, do not panic. You can request a smaller amount, a longer repayment period, or collect overdue invoices first. A good financing plan fits your cash flow, not the other way round.
Step 5: Choose the Right Financing Product
The reason you need the money should decide the type of loan you choose. Matching purpose and product keeps your repayments in step with the way the money earns its return. Here are the three common options for business financing Singapore SMEs consider.
- Working capital loan: This suits day to day cash flow needs such as buying stock, paying suppliers or covering salaries while customers pay late. A working capital loan Singapore usually has a shorter tenure and aims to bridge a gap in operating cash.
- Term loan: This suits planned business investment such as equipment, renovation or expansion. A business term loan usually has fixed instalments over a longer period, so you can match repayments to the years the asset will earn income.
- Trade financing: This suits eligible trade transactions such as paying overseas suppliers or fulfilling confirmed purchase orders. Lenders usually tie the facility to the underlying trade documents.
Whichever product you pick, look beyond the advertised interest rate. Two loans with the same headline rate can cost very different amounts once you add fees. Ask each lender for the total amount you will repay, and compare these items side by side.
| Compare | Questions to ask |
| Total financing cost | What is the total amount I will repay over the full term, including interest and fees? |
| Interest basis | Is the rate flat or reducing balance, and is it fixed or floating? |
| Repayment period | How many months, and what is each monthly instalment? |
| Fees | Is there a processing fee, legal fee, insurance cost or documentation fee? |
| Early repayment | Is there a penalty if I pay off the loan sooner? |
| Late payment | What charges apply if I miss an instalment? |
| Security or guarantee | Does the lender need collateral or a personal guarantee from the directors? |
If you are not sure which product fits, a business loan consultancy Singapore adviser can help you compare the options using your own numbers.
Step 6: Avoid Common Application Mistakes
Most application problems come from a handful of avoidable mistakes. Here are the ones we see most often, together with a simple fix for each.
- Incomplete documents: Missing pages from a bank statement or an unsigned form slow everything down. Fix: tick off each item on the checklist below and check that every page is there.
- Inconsistent financial figures: Different revenue numbers in different documents make lenders doubt the rest of the file. Fix: reconcile your records first and prepare a short explanation for any gap.
- Unrealistic cash flow projections: A forecast that doubles sales overnight looks hopeful rather than reliable. Fix: base your projections on past results and confirmed orders, and show a cautious case as well as a best case.
- An unclear funding purpose: A request for “working capital” with no detail leaves lenders guessing. Fix: state what you will buy, how much it costs and when you expect to recover the cash.
- Applying without understanding the eligibility criteria: Every rejected application can leave a trace on your credit record, and enquiries may be visible to other lenders. Fix: read the lender’s requirements first, and apply only when you meet them.
- Applying to many lenders at once: Several enquiries in a short time can look like financial stress. Fix: shortlist two or three suitable lenders, then apply in a planned order.
Step 7: Use a Business Loan Readiness Checklist
Print this checklist and tick each box before you apply. If you can tick most of them, you are in a strong position to start the conversation with a lender.
| Area | Check | Done |
| Documents | ACRA business profile downloaded and current | ☐ |
| Documents | Latest financial statements ready (profit and loss, balance sheet) | ☐ |
| Documents | Recent company bank statements saved for every month requested | ☐ |
| Documents | Management accounts updated to last month | ☐ |
| Documents | Directors’ or guarantors’ ID and Notices of Assessment ready where needed | ☐ |
| Documents | Debtors and creditors ageing reports printed | ☐ |
| Financial review | Bookkeeping up to date and bank transactions matched | ☐ |
| Financial review | Overdue invoices followed up and noted | ☐ |
| Financial review | Figures consistent across all documents, with notes on differences | ☐ |
| Funding needs | Purpose written in one clear sentence | ☐ |
| Funding needs | Amount calculated, with quotations or purchase orders to support it | ☐ |
| Repayment planning | Monthly cash flow tested against the new instalment | ☐ |
| Repayment planning | Existing loan commitments listed with balances and instalments | ☐ |
| Lender checks | Eligibility criteria read and met for each lender or scheme | ☐ |
| Lender checks | Total cost, fees and early repayment terms compared | ☐ |
Get a Second Pair of Eyes Before You Submit
Your application usually gets only one first impression, so it helps to check your file before a lender does. At Bizsquare Management Consultants, we combine accounting know how with practical financing experience, so we can read your numbers the way a lender might.
Our team can support you in three ways:
- Review your financial information: We go through your financial statements, bank records and ageing reports, and point out gaps or inconsistencies you may want to explain before you apply.
- Explain your financing options: We walk you through the difference between a working capital loan for operating cash flow and a business term loan for planned investment, using plain language and your own figures.
- Prepare you for lender discussions: We help you organise your documents, write a clear funding purpose and get ready for the questions lenders commonly ask.
Every business is different, and each lender makes its own credit decision. We cannot promise loan approval or guaranteed financing, but we can help you approach the process with clearer numbers and better preparation. Speak with Us today and start your loan preparation on the right foot.
Frequently Asked Questions
1.) What documents do I need for a business loan application in Singapore?
Most lenders ask for your ACRA business profile, latest financial statements, recent company bank statements, existing loan details, directors’ identification and personal Notices of Assessment where required. They may also ask for management accounts, debtors and creditors ageing reports, and a business plan or quotations that explain the funding purpose. Exact SME loan documents Singapore lenders request differ by lender and loan product.
2.) What are the basic business loan requirements in Singapore?
Common requirements include a company registered and operating in Singapore, a minimum operating history, acceptable turnover, a satisfactory credit record and the ability to repay. Government-supported schemes may add rules on local ownership and company size. Check the lender’s current criteria, because business loan requirements Singapore lenders use are not the same everywhere.
3.) How do lenders decide business loan eligibility in Singapore?
Lenders review your revenue trend, profit, cash flow, existing debts, credit history and business stability. They also check that the funding purpose is clear and that your cash flow can cover repayments. Each lender weighs these factors in its own way, so the same company may get different results from different lenders.
4.) How long does it take to prepare for a business loan application?
If your bookkeeping is current, you may gather documents in a few days. If your records are behind, it can take a few weeks to update accounts and reconcile figures. Starting early gives you time to fix problems before a lender sees them.
5.) How many months of bank statements do lenders usually ask for?
Many lenders ask for the last 6 to 12 months of company bank statements, though some ask for fewer or more. Confirm the number with your lender before you download them, and make sure each statement is complete.
6.) Do I need a personal guarantee from the directors?
Some lenders ask for a personal guarantee, especially for smaller or younger companies, while others may not for certain products. If one is needed, directors will usually provide identification and personal financial documents such as the Notice of Assessment.
7.) Can a new company apply for a business loan?
Yes, but options may be more limited. Many lenders prefer a minimum operating history, often at least six months to a year, though this varies. A newer company can strengthen its application with clear bank records, confirmed orders and a realistic business plan.
8.) Will a poor credit history stop me from getting financing?
It can make approval harder, but each lender looks at the full picture. You can improve your position by clearing overdue amounts, paying bills on time and explaining any past problems honestly. Checking your own credit report first helps you know what lenders will see.
9.) How much can my SME borrow?
The amount depends on your revenue, cash flow, existing debts, the loan type and the lender’s policy. A practical approach is to calculate what you need for a specific purpose, then test whether your monthly cash flow can comfortably cover the instalments.
10.) What is a working capital loan in Singapore?
A working capital loan Singapore businesses use is a loan that finances daily operating needs, such as buying inventory, paying suppliers or covering payroll while customers pay late. It usually has a shorter repayment period than a loan for long term investment.
11.) What is the difference between a working capital loan and a term loan?
A working capital loan supports operating cash flow, while a term loan usually funds planned investments such as equipment or expansion, with fixed instalments over a longer period. Choosing the one that matches your purpose helps your repayments line up with the way the money earns returns.
12.) What fees should I look for besides the interest rate?
Ask about processing fees, legal or documentation fees, insurance, early repayment charges and late payment charges. Ask each lender for the total amount you will repay, so you can compare offers fairly instead of looking only at the advertised rate.
13.) Do I need audited accounts to apply?
Not always. Many small companies qualify for audit exemption, and lenders may accept unaudited financial statements together with management accounts. Policies differ, so ask your lender which format they accept.
14.) Can Bizsquare guarantee my loan approval?
No. Each lender makes its own credit decision, and no consultant can promise approval or guaranteed financing. Bizsquare can help you review your financial information, understand your financing options and prepare for discussions with potential lenders.